Technical guide
IPv4 Market by Region in 2026: Where Are Address Transfers Most Active?
The IPv4 secondary market is global, but IPv4 transfer activity is not distributed evenly across every Regional Internet Registry.
Organizations operating under RIPE NCC, ARIN, APNIC, LACNIC and AFRINIC participate in different registry environments, and historical transfer activity varies substantially between them.
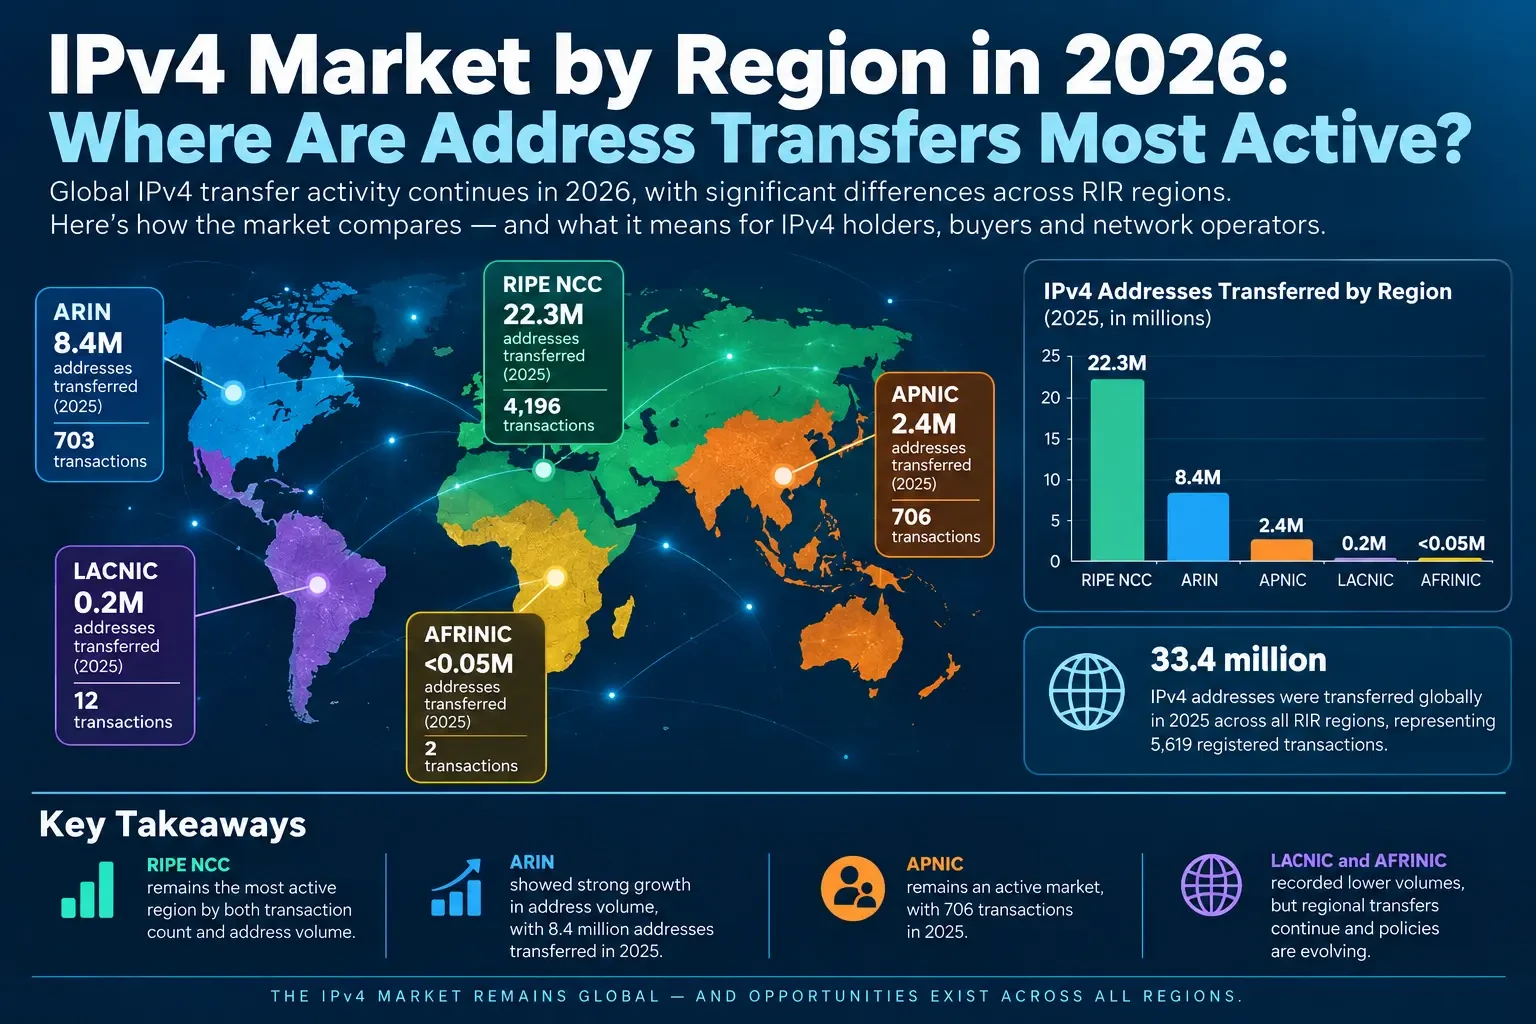
The latest complete cross-RIR dataset shows a particularly strong concentration of IPv4 transfer activity in the RIPE NCC service region, while ARIN recorded significant growth in transferred address volume and APNIC remained an active but smaller market by total addresses moved.
For IPv4 holders, these regional differences matter.
The registry associated with a resource can influence:
- available transfer paths;
- documentation requirements;
- buyer eligibility;
- inter-RIR options;
- transaction execution; and
- the potential buyer pool.
But regional transfer statistics need to be interpreted carefully.
A registry region does not determine where an IPv4 block can be routed, and high transfer activity does not automatically mean every block in that region will sell quickly.
This article examines the latest available IPv4 transfer data, compares market activity across the five RIR regions, and explains what those differences mean for IPv4 buyers and sellers in 2026.
IPv4 Market by Region in 2026: Quick Answer
The latest complete dataset that allows all five RIRs to be compared on the same basis covers 2025 transfer activity and was published in January 2026.
It recorded approximately:
| Receiving RIR | 2025 Transfer Transactions | IPv4 Addresses Transferred |
|---|---|---|
| RIPE NCC | 4,196 | 22.3 million |
| ARIN | 703 | 8.4 million |
| APNIC | 706 | 2.4 million |
| LACNIC | 12 | 0.2 million |
| AFRINIC | 2 | Less than 0.05 million* |
| Total | 5,619 | 33.4 million |
*The published dataset rounds AFRINIC's 2025 volume to 0.0 million.
On this basis, RIPE NCC was by far the most active receiving RIR in both transaction count and total IPv4 address volume. ARIN and APNIC recorded almost the same number of transactions—703 and 706 respectively—but ARIN transfers represented substantially more IPv4 addresses.
The 2026 picture remains incomplete because the year is still in progress and different RIRs publish current-year statistics in different formats.
However, RIPE NCC's monthly reports already show continued substantial activity. It reported:
- January: 908,800 addresses
- February: 1,524,224
- March: 1,789,824
- April: 2,874,112
- May: 1,913,088
- June: 1,775,872
- July: 5,935,616
Together, those reports represent approximately 16.72 million IPv4 addresses transferred through July 2026 in the RIPE NCC environment.
The key conclusion is therefore:
RIPE NCC remains the clearest center of registered IPv4 transfer activity, while ARIN represents an increasingly important source of large-volume transfers and APNIC continues to maintain an established secondary transfer market.
How Are Regional IPv4 Transfers Measured?
Before comparing regions, it is important to define what the numbers mean.
Regional Internet Registries record IPv4 transfers because registry information needs to reflect changes in the organizations responsible for Internet number resources.
However, different statistics can measure different things.
Transfer Transactions
This counts individual registered transfer events.
One transaction can involve one block or multiple prefixes.
IPv4 Address Volume
This measures how many individual IPv4 addresses were represented by registered transfers.
A single large transfer can therefore outweigh dozens of smaller transactions.
Blocks Transferred
Some RIR publications count individual prefixes or blocks rather than transactions.
This number should not automatically be compared with a dataset counting complete transfer events.
Inter-RIR Transfers
These involve resources moving between organizations registered in different RIR service environments.
Intra-RIR Transfers
These occur within the same RIR framework.
The cross-RIR dataset used in this article counts registered transfers according to the receiving RIR. It includes intra-RIR and inter-RIR transactions as well as certain transfers associated with mergers and acquisitions.
For that reason, the figures should be viewed as a measure of registered transfer activity, not as a perfect representation of every private commercial arrangement involving IPv4.
1. RIPE NCC: The Most Active IPv4 Transfer Region
The clearest result in the latest cross-RIR data is the scale of activity associated with the RIPE NCC service region.
In 2025, the dataset recorded:
4,196 transfer transactions
representing:
22.3 million IPv4 addresses
That accounted for approximately three-quarters of the 5,619 transfer transactions in the global dataset.
It also represented roughly two-thirds of the 33.4 million addresses transferred across all five RIRs.
This is not a one-year anomaly.
RIPE NCC has consistently recorded high transfer activity over the past decade.
For example, transfer counts associated with the region reached:
- 4,221 in 2019;
- 4,696 in 2020;
- 5,742 in 2021;
- 4,937 in 2023;
- 5,215 in 2024; and
- 4,196 in 2025.
Transfer volume has also regularly reached tens of millions of addresses per year.
RIPE NCC Transfer Activity Remains Strong in 2026
The 2026 monthly data reinforces that picture.
One particularly striking month was July 2026, when RIPE NCC reported:
5,935,616 IPv4 addresses transferred
compared with 1,775,872 in June.
That does not mean July represents a permanent new monthly baseline.
Large transfers can cause substantial month-to-month variation.
Instead, the data illustrates an important characteristic of the IPv4 market:
Transfer volume can be highly concentrated in individual transactions or months.
This is one reason annual and multi-year trends are more useful than judging market health from a single month.
RIPE NCC also publishes detailed public transfer records containing transferred prefixes, sending organizations, receiving organizations, country codes, transfer type and processing date.
2. ARIN: Growing Importance in IPv4 Transfer Volume
ARIN presents a different but equally interesting market story.
The cross-RIR dataset recorded:
703 transactions in 2025
representing approximately:
8.4 million IPv4 addresses
The transaction count was almost identical to APNIC's 706.
But ARIN's total address volume was approximately 3.5 times larger.
That tells us something important:
Transaction count alone does not show the size of the IPv4 market moving through a region.
ARIN's address volume increased significantly from approximately 4.5 million addresses in 2024 to 8.4 million in 2025.
The APNIC analysis of global RIR transfer data specifically notes that transfer volume associated with the ARIN region has been growing.
ARIN also publishes current 2026 statistics for:
- in-region IPv4 transfers;
- inter-RIR transfers into ARIN;
- inter-RIR transfers out of ARIN;
- transfer requests; and
- processed transfer tickets.
Why ARIN Matters to the Global IPv4 Market
The ARIN region contains a substantial amount of historically allocated IPv4 address space.
As organizations restructure networks, consolidate infrastructure, migrate workloads or determine that some IPv4 assets are no longer operationally necessary, portions of that address space can become available for transfer.
Inter-RIR transfer mechanisms can also allow eligible resources to move between registry environments where applicable policies are compatible.
For sellers, this makes ARIN especially important when evaluating:
- large legacy holdings;
- enterprise IPv4 portfolios;
- institutional sellers;
- inter-RIR transactions; and
- larger block transactions.
However, the presence of a large regional transfer market does not mean every ARIN-administered block has the same commercial value.
CIDR size, transfer eligibility, registration status, reputation and market demand still matter.
For a broader look at how block size affects marketability, see LARUS's IPv4 Liquidity in 2026.
3. APNIC: Active Market, Lower Address Volume Than Past Peaks
APNIC remains an established IPv4 transfer market.
The latest complete cross-RIR dataset recorded:
706 transfer transactions in 2025
representing approximately:
2.4 million IPv4 addresses
Interestingly, APNIC recorded slightly more transactions than ARIN—706 versus 703—but significantly less total address volume.
That is another example of why market activity should never be measured by a single metric.
APNIC's 2025 Annual Report separately states that APNIC processed 696 IPv4 market transfers and 269 merger-and-acquisition IPv4 transfers during 2025. Different reporting methodologies can therefore produce different totals depending on which categories are being counted.
For cross-regional comparison, this article keeps one consistent dataset rather than mixing those definitions.
APNIC Transfer Volume Has Declined From Earlier Peaks
The longer-term data is also notable.
The APNIC receiving region recorded approximately:
- 16.6 million transferred addresses in 2020;
- 6.5 million in 2021;
- 3.7 million in 2022;
- 2.7 million in 2023;
- 2.5 million in 2024; and
- 2.4 million in 2025.
That does not mean IPv4 has stopped being commercially or operationally important in Asia Pacific.
Instead, it shows that registered transfer volume has changed significantly from the exceptional levels seen earlier in the decade.
APNIC itself reported in 2026 that transfer activity remained high relative to the ten-year trend, although the amount of IPv4 transferred during 2025 was lower than in 2023 and 2024.
APNIC maintains daily transfer logs recording resource, source organization, destination organization, source and destination economy, RIR and transfer date.
4. LACNIC: Smaller Transaction Market, but Regional Transfers Continue
LACNIC represents a much smaller portion of the global transfer dataset when measured by transaction count.
The cross-RIR analysis recorded:
12 transactions in 2025
and approximately:
0.2 million transferred IPv4 addresses.
This should not be interpreted to mean there are only a handful of individual address blocks changing registration in Latin America and the Caribbean.
Different sources use different units.
For example, LACNIC reported 197 blocks transferred during 2024, a 25% increase from 2023. LACNIC also noted that a greater number of/24blocks were involved, helping explain why transaction activity could rise without a comparable increase in total address volume.
This demonstrates why:
blocks, transactions and total addresses should never be treated as interchangeable statistics.
What LACNIC Data Tells Sellers
The smaller regional market does not automatically make a LACNIC-administered IPv4 resource unattractive.
A seller needs to evaluate the specific transfer path available to the block.
Relevant questions include:
- Is the block eligible for transfer?
- Can it participate in an inter-RIR transfer?
- Which receiving organizations are eligible?
- What is the CIDR size?
- Is the block actively routed?
- Are registry records current?
- Is there demand from qualified counterparties?
The commercial market for a particular resource can therefore be broader than its local registry region alone.
5. AFRINIC: A Transfer Environment That Is Changing in 2026
AFRINIC historically shows the smallest recorded transfer activity in the cross-RIR dataset.
For 2025, the dataset showed:
2 registered transactions
with total volume rounded to less than 0.1 million addresses.
However, 2026 is particularly important for AFRINIC because its transfer-policy environment is changing.
In February 2026, AFRINIC ratified a Number Resources Transfer Policy covering specified intra-regional and inter-RIR transfer scenarios.
AFRINIC reported in mid-2026 that implementation was underway and that the technical implementation of the broader policy would depend in part on deployment of its new systems.
This means historical AFRINIC transfer volumes should not automatically be used to predict future market behavior.
The policy and operational environment is evolving.
For a transaction taking place now, organizations should verify the current implemented process directly with the registry rather than relying on historical assumptions.
Which RIR Has the Most Active IPv4 Market?
Using the latest complete cross-RIR dataset, the answer is clear.
By Transaction Count
- RIPE NCC — 4,196
- APNIC — 706
- ARIN — 703
- LACNIC — 12
- AFRINIC — 2
By IPv4 Address Volume
- RIPE NCC — 22.3 million
- ARIN — 8.4 million
- APNIC — 2.4 million
- LACNIC — 0.2 million
- AFRINIC — less than 0.1 million as rounded in the dataset
The two rankings are similar, but one difference is important:
APNIC narrowly exceeded ARIN in transaction count, while ARIN moved substantially more IPv4 address space.
That illustrates why sellers should ask not only:
Where are the most transfers occurring?
but also:
What type and size of resources are moving through that market?
Regional Transfer Activity Does Not Mean IPv4 Is Geographically Locked
An IPv4 registry record and the physical location where a network operates are not the same thing.
A resource may be administered through one RIR environment while being used by infrastructure serving customers across multiple countries.
Likewise, BGP determines how a prefix is announced and propagated through networks.
Registry administration performs a different coordination function.
This distinction matters because the IPv4 market involves several separate layers:
Commercial transaction
→ buyer and seller agree on terms
Registry transfer
→ applicable registry records are updated
Routing and security updates
→ BGP, RPKI, IRR and related records may need to change
Operational deployment
→ the receiving organization uses the resource in its network
A completed registry transfer therefore does not by itself describe every aspect of how the address space is being used operationally.
For organizations selling IPv4, these layers should be planned together.
What Is an Inter-RIR IPv4 Transfer?
An inter-RIR transfer involves an IPv4 resource moving between organizations associated with different Regional Internet Registries.
For example, a qualifying transaction could involve a resource moving from an organization administered through one RIR to an eligible recipient under another.
Inter-RIR transactions can expand the possible buyer pool for certain resources.
However, they depend on:
- compatible RIR policies;
- resource eligibility;
- recipient eligibility;
- documentation;
- current registry status; and
- applicable transfer procedures.
Not every IPv4 resource automatically has access to every regional market.
For more detail on registry roles, see LARUS's guide to ARIN, RIPE and APNIC in IPv4 Transfers.
What Does Regional IPv4 Market Data Mean for Sellers?
Regional statistics are most useful when they help an IPv4 holder make a better transaction decision.
They should not be used to conclude:
"My region is active, therefore my block will sell immediately."
Instead, use regional data as one part of a broader evaluation.
1. Identify the Current RIR
Confirm whether the resource is currently administered through:
- ARIN;
- RIPE NCC;
- APNIC;
- LACNIC; or
- AFRINIC.
2. Confirm Transfer Eligibility
The availability of a buyer does not matter if the intended transfer cannot satisfy the relevant registry process.
3. Determine Whether Inter-RIR Options Exist
An eligible cross-RIR path may increase the potential buyer pool.
But compatibility must be checked for the specific transaction.
4. Evaluate the Block Size
Regional volume data tells you where addresses are moving.
Block-size data helps answer a different question:
Which prefixes may attract the widest buyer pool?
LARUS examines that separately in IPv4 Liquidity in 2026: Which Block Sizes Are Moving Fastest in the Market?.
5. Review Registry Records
Before marketing a block, confirm:
- organization details;
- resource records;
- registration status; and
- corporate authority.
Outdated WHOIS or RDAP information can introduce additional transaction friction.
6. Review Operational Dependencies
Check:
- BGP announcements;
- origin ASN;
- ROAs;
- IRR route objects;
- reverse DNS; and
- production systems using the addresses.
7. Compare Current Market Pricing
High regional transfer volume does not establish a universal price.
For current market context, see LARUS's Global IPv4 Pricing & Market Statistics.
What Does Regional Transfer Activity Mean for Buyers?
Buyers should use the same data differently.
A high-volume region may indicate an established transfer ecosystem, but buyers still need to assess the specific resource.
Before acquiring IPv4, consider:
- CIDR size;
- registry region;
- inter-RIR compatibility;
- reputation;
- routing history;
- RPKI status;
- IRR state;
- documentation;
- price; and
- deployment timeline.
The lowest-priced block is not automatically the easiest block to deploy.
And a highly active regional market does not eliminate the need for resource-level due diligence.
Why RIPE and ARIN Volume Matters for the Global IPv4 Secondary Market
The data shows that IPv4 redistribution is not a marginal phenomenon.
Across the RIR transfer logs, approximately 33.4 million IPv4 addresses were represented in registered transfers during 2025.
Since 2012, the aggregate number of addresses appearing in transfer logs reached approximately 342 million, equivalent to about 9.3% of the 3.7 billion delegated IPv4 addresses.
That figure can count the same resource more than once when it is transferred multiple times, so it should not be interpreted as 342 million unique addresses permanently changing hands.
Even with that limitation, the scale shows how important secondary redistribution has become after exhaustion of large free IPv4 pools.
IPv4 scarcity did not cause the address space to become static.
Instead, existing resources continue to move between organizations.
Is a High-Transfer Region Automatically a Better Place to Sell IPv4?
No.
A regional market with more recorded transactions may provide a larger or more mature pool of potential counterparties.
But the outcome for one seller depends on the individual resource.
Consider two hypothetical blocks:
Block A
- Located in a highly active RIR market
- Poor documentation
- Significant reputation issues
- Unrealistic seller valuation
- Complicated production dependencies
Block B
- Located in a smaller transfer market
- Clear registration
- Transfer eligible
- Clean operational history
- Realistic pricing
- Compatible inter-RIR path
Block B may ultimately be easier to transact.
Regional activity is therefore a market signal, not a substitute for due diligence.
IPv4 Transfer Market Checklist by Region
Before selling an IPv4 portfolio, ask:
- Which RIR currently administers the block?
- Is it eligible for an intra-RIR transfer?
- Is an inter-RIR transfer possible?
- Which RIR would the buyer use?
- Are current policies reciprocal and compatible?
- What is the CIDR size?
- Are registry records current?
- Is corporate authority clear?
- Is the prefix currently routed?
- Which origin ASN announces it?
- Are ROAs active?
- Which IRR route objects exist?
- Is reverse DNS configured?
- Is the block genuinely surplus?
- Does it have historical reputation issues?
- What current buyer demand exists?
- Is the asking price aligned with the market?
- Will the organization still need IPv4 after the transaction?
For a complete seller workflow, see How to Sell IPv4 Addresses in 2026.
Frequently Asked Questions
Which region has the most IPv4 transfers?
In the latest complete cross-RIR dataset, the RIPE NCC region had the highest number of registered transfer transactions and the largest volume of IPv4 addresses transferred during 2025.
How many IPv4 addresses were transferred through RIPE NCC in 2025?
The cross-RIR dataset reported approximately 22.3 million addresses associated with RIPE NCC as the receiving RIR.
How active is RIPE NCC in 2026?
RIPE NCC reported monthly transfer volumes ranging from 908,800 addresses in January to approximately 5.94 million in July. Summed through July, its published monthly figures represent roughly 16.72 million IPv4 addresses.
How active is the ARIN IPv4 transfer market?
The latest complete cross-RIR dataset recorded 703 transactions and approximately 8.4 million transferred IPv4 addresses for ARIN in 2025, up substantially in address volume from 2024.
How many IPv4 transfers occurred in APNIC?
The comparable cross-RIR dataset recorded 706 transactions in 2025. APNIC's own annual reporting uses additional categories and reports 696 market transfers plus 269 merger-and-acquisition transfers, illustrating why methodologies need to be compared carefully.
Is RIPE NCC the biggest IPv4 market?
It was the largest receiving RIR in the latest comparable dataset by both transaction count and total transferred address volume. That does not mean every commercial IPv4 transaction globally is visible in these records.
Can IPv4 addresses move between RIR regions?
Yes, in some circumstances. Inter-RIR transfers are possible when applicable registry policies and eligibility requirements allow the transaction.
Does the RIR determine where an IP address can be used?
Not in the simple sense of physical network location. RIRs maintain registration and coordination frameworks, while actual routing depends on network operation and BGP announcements.
Does a high-volume region mean my IPv4 block is worth more?
Not necessarily. Block size, transferability, reputation, demand, documentation and prevailing pricing all affect commercial value.
Which factors matter most when selling IPv4?
Sellers should evaluate RIR, transfer eligibility, CIDR size, buyer demand, registry records, routing, RPKI, IRR, reputation and operational dependencies.
How can I sell surplus IPv4 addresses?
Begin by inventorying the resource, confirming the RIR and transfer path, preparing documentation and reviewing operational dependencies. Organizations with qualifying surplus IPv4 can also sell IPv4 addresses to LARUS.
Conclusion
IPv4 transfer activity in 2026 is global, but it is far from evenly distributed.
The latest complete comparable RIR data shows:
RIPE NCC leading both transaction count and total address volume.
ARIN has become increasingly significant by address volume.
APNIC remains an established secondary transfer environment, although volumes are below earlier peaks.
LACNIC continues to support regional and inter-RIR redistribution at a smaller recorded scale.
AFRINIC enters a particularly important period in 2026 as its newly ratified transfer framework progresses through implementation.
But regional rankings only tell part of the story.
For an individual IPv4 seller, marketability depends on the intersection of:
RIR + transfer path + block size + registry readiness + buyer demand + price + operational state
That is why IPv4 holders should evaluate the resource itself rather than treating regional averages as a guaranteed transaction outcome.
If your organization holds surplus/24,/20,/16or larger IPv4 resources, Sell IP Addresses to LARUS to discuss the portfolio and available transaction options.
For additional 2026 market analysis, read IPv4 Liquidity in 2026: Which Block Sizes Are Moving Fastest in the Market?.
Production IPv4
Need IPv4 for a live network?
Check available capacity, then choose the Continuity level that matches the cost of disruption and renumbering.